FREE PLAYBOOK FOR HIGH-INCOME T4 EMPLOYEES
YOUR HOME EQUITY
IS SITTING IDLE.
SO IS YOUR TAX BRACKET.
Most high earners throw every spare dollar at the mortgage. This free playbook shows you what your equity and your bracket could be doing instead: working together, building an invested portfolio, without earning an extra dollar at work.
Free. Instant. Nothing to buy, no call required to read it.
Just math your bank has never laid out.
Free. Instant. Nothing to buy, no call required to read it. Just math your bank has never laid out.
Written by a dual-licensed mortgage broker and financial advisor, for the salaried high earners doing the money math at 9pm after the kids are down.
THE TWO CHOICES
You have $10,000 of spare money.
You have two options.
option one
PUT IT AGAINST
THE MORTGAGE
You save about $500 in interest this year. That's the entire return. Small, certain, and gone.
option two
put it to work
It earns a return in the market, becomes an asset you actually own, and, structured properly, the cost of the money you use is generally tax-deductible.
For a household earning well and sitting on real equity, the second path is the one your bank has never laid out in plain numbers. The playbook lays it out.
THE TWO CHOICES
You have $10,000 of spare money.
You have two options.
Put it against the mortgage
You save about $500 in interest this year. That's the entire return. Small, certain, and gone.
PUT IT TO WORK
It earns a return in the market, becomes an asset you actually own, and, structured properly, the cost of the money you use is generally tax-deductible.
For a household earning well and sitting on real equity, the second path is the one your bank has never laid out in plain numbers. The playbook lays it out.
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
The Two Assets You Own That Earn Nothing
Your equity has been sitting in drywall earning 0% since the day you bought. Your tax bracket has been treated as pure pain. The playbook shows you both as what they actually are: the two halves of an engine.
The Move Your Bank Has Never Laid Out
The worked example, in round numbers: how accessed equity gets put to work so you keep the difference between what money costs and what it earns. Every figure labelled, every figure checkable.
Why Your Bracket Is The Lever, And Yours Runs At Full Strength
Past $181,440 of individual income in Ontario, the tax system starts paying its biggest rewards on exactly the moves you're now positioned to make. Deductible borrowing costs. A $10,000 RRSP contribution returning roughly $4,800. Per person.
The Honest Limits
What this strategy is, what it costs, where the risk lives, and who it's wrong for. Written plainly, because you were going to stress-test it anyway.
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
The Two Assets You Own That Earn Nothing
Your equity has been sitting in drywall earning 0% since the day you bought. Your tax bracket has been treated as pure pain. The playbook shows you both as what they actually are: the two halves of an engine.
The Move Your Bank Has Never Laid Out
The worked example, in round numbers: how accessed equity gets put to work so you keep the difference between what money costs and what it earns. Every figure labelled, every figure checkable.
Why Your Bracket Is The Lever, And Yours Runs At Full Strength
Past $181,440 of individual income in Ontario, the tax system starts paying its biggest rewards on exactly the moves you're now positioned to make. Deductible borrowing costs. A $10,000 RRSP contribution returning roughly $4,800. Per person.
The Honest Limits
What this strategy is, what it costs, where the risk lives, and who it's wrong for. Written plainly, because you were going to stress-test it anyway.
WHAT
YOU'LL
LEARN
The Two Assets You Own That Earn Nothing
Your equity has been sitting in drywall earning 0% since the day you bought. Your tax bracket has been treated as pure pain. The playbook shows you both as what they actually are: the two halves of an engine.
The Move Your Bank Has Never Laid Out
The worked example, in round numbers: how accessed equity gets put to work so you keep the difference between what money costs and what it earns. Every figure labelled, every figure checkable.
Why Your Bracket Is The Lever, And Yours Runs At Full Strength
Past $181,440 of individual income in Ontario, the tax system starts paying its biggest rewards on exactly the moves you're now positioned to make. Deductible borrowing costs. A $10,000 RRSP contribution returning roughly $4,800. Per person.
The Honest Limits
What this strategy is, what it costs, where the risk lives, and who it's wrong for. Written plainly, because you were going to stress-test it anyway.
WHO THIS PLAYBOOK IS FOR
WHO THIS
PLAYBOOK IS FOR
Salaried T4 employees earning $180K+ individually who watch half of every bonus disappear and still feel like they're standing still
Homeowners with real equity built up, currently earning nothing, locked in drywall
Anyone with at least 10 years of runway before they want to stop working
The ones with spare cash flow going to the mortgage, savings, or nowhere in particular, on autopilot
WHY YOU NEED
THIS PLAYBOOK
You did everything right. Strong career, real equity, payments on time, RRSP topped up when the accountant said so.
And the wealth never seems to compound. The equity sits idle. The bracket takes half of every bonus. The refund evaporates every April. Your money works hard for everyone except you.
Your bank had no reason to show you a different position. The default is their margin.
This playbook is where you finally see it. Your equity and your bracket, on the same page, working.
THIS WORKS EVEN IF...
Even if your renewal is years away. The position conversation works at any point in the mortgage, and every year of waiting is a year the gap compounds against you.
Even if you've watched hours of the YouTube videos. Those show you one piece at a time. The playbook puts the whole engine on one page: the equity, the structure, the tax layer, in order.
Even if you already have an advisor. Ask them one question: has your mortgage ever appeared in your investment plan? If the answer is no, this playbook is the missing page.
Especially if you like to check the math. Every figure is labelled, illustrative, and built to be verified. The math surviving inspection is the whole pitch.
THIS WORKS EVEN IF...
Even if your renewal is years away. The position conversation works at any point in the mortgage, and every year of waiting is a year the gap compounds against you.
Even if you've watched hours of the YouTube videos. Those show you one piece at a time. The playbook puts the whole engine on one page: the equity, the structure, the tax layer, in order.
Even if you already have an advisor. Ask them one question: has your mortgage ever appeared in your investment plan? If the answer is no, this playbook is the missing page.
Especially if you like to check the math. Every figure is labelled, illustrative, and built to be verified. The math surviving inspection is the whole pitch.
Why did my bank never show me this?
That question is the reason this playbook exists.
WHAT'S INSIDE
01
The Two Choices
The $10,000 fork every high earner faces monthly, and what each path actually returns.
02
Your Idle Assets
Two fill-in lines that show you, in pen, what's been sitting still: your equity and your bracket.
03
The Mechanic
The worked example with round numbers, including the illustrative spread between a ~5% borrowing cost and a ~10% portfolio, and the risk disclosure that keeps it honest.
04
The Tax Layer
Why this is built for your bracket specifically: generally-deductible borrowing costs, and the ~$4,800 that comes back on a $10,000 RRSP contribution past the line.
05
What This Is Not
The honest limits: where the risk lives, why the portfolio is boring on purpose, and why faster mortgage payoff is a preference rather than the point.
06
The Two Positions
Where you are now next to the restructured position, on one page. The page worth showing your spouse.
DON'T WAIT. GET THE IDLE EQUITY PLAYBOOK NOW.
Click the button for instant access, and see your house and your income slip differently in the next 10 minutes.
WHAT'S INSIDE
01
The Two Choices
The $10,000 fork every high earner faces monthly, and what each path actually returns.
02
Your Idle Assets
Two fill-in lines that show you, in pen, what's been sitting still: your equity and your bracket.
03
The Mechanic
The worked example with round numbers, including the illustrative spread between a ~5% borrowing cost and a ~10% portfolio, and the risk disclosure that keeps it honest.
04
The Tax Layer
Why this is built for your bracket specifically: generally-deductible borrowing costs, and the ~$4,800 that comes back on a $10,000 RRSP contribution past the line.
05
What This Is Not
The honest limits: where the risk lives, why the portfolio is boring on purpose, and why faster mortgage payoff is a preference rather than the point.
06
The Two Positions
Where you are now next to the restructured position, on one page. The page worth showing your spouse.
DON'T WAIT. GET THE IDLE EQUITY PLAYBOOK NOW.
Click the button for instant access, and see your house and your income slip differently in the next 10 minutes.
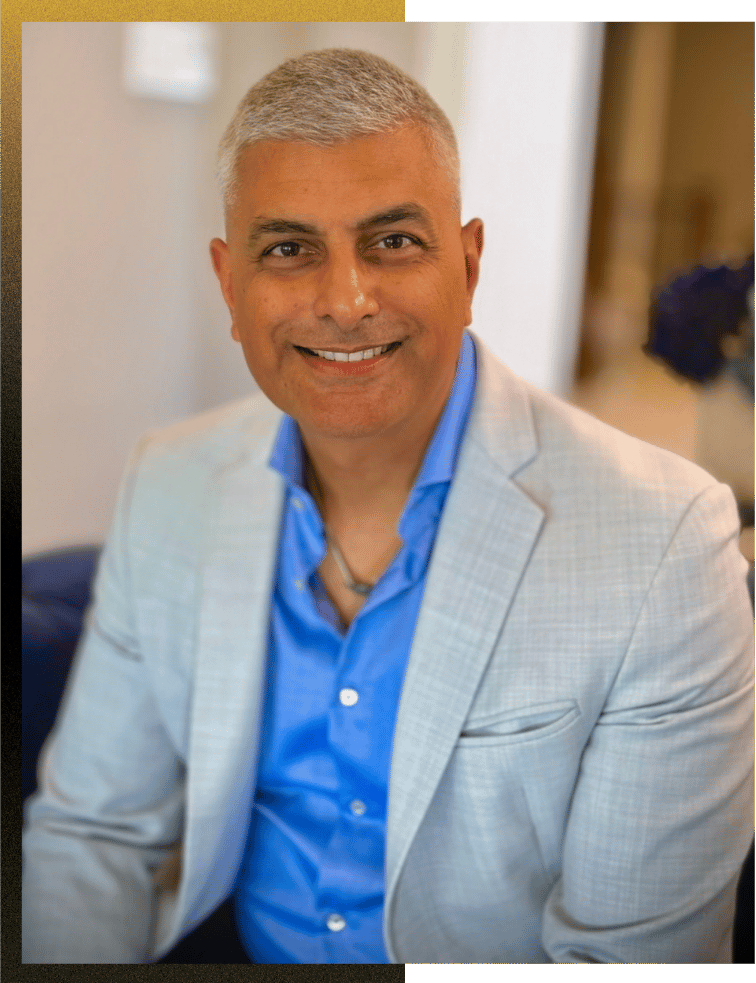
THE PERSON BEHIND THE PLAYBOOK
I'm Steve
Balgobind
I'm Steve Balgobind
I hold both licences, mortgage broker and financial advisor, and that combination is the entire point. The industry splits your money into departments: the broker handles the debt and hands you off, the advisor grows the portfolio and never sees the mortgage, and the accountant shows up in April to report the damage. No single person was ever responsible for making the pieces work together.
My files are engineers, physicians, lawyers, and directors across the GTA. They come to me because I sit on both sides of the table, and they stay because everything I build runs on math they can verify.
I run this exact structure on my own home. My mortgage, my equity, my bracket, wired the same way this playbook describes. I'm recommending a strategy I carry myself, not one I read about.
Ready To Put Both Of Them To Work?
Get The Idle Equity Playbook now. In 10 minutes you'll understand more about what your equity and your bracket could be doing than the last 10 years of statements have shown you.
Ready To Put Both Of Them To Work?
Get The Idle Equity Playbook now. In 10 minutes you'll understand more about what your equity and your bracket could be doing than the last 10 years of statements have shown you.
Init Capital Funding · Steve Balgobind, Licensed Mortgage Broker + Licensed Financial Advisor · 8Twelve Mortgage License # 13072 · Serving the GTA
The Idle Equity Playbook contains illustrative examples, not projections or guarantees. Returns are not guaranteed and borrowing to invest carries risk, including the risk that investment returns are lower than the cost of borrowing. Whether any strategy is suitable depends on your individual circumstances. This site is not part of, or endorsed by, Facebook, Google, or any social media platform in any way.